ACH vs Wire Transfer vs Credit Card Fees: The B2B Payment Cost Guide (2026)
Compare ACH Direct Debit vs bank wire vs credit card processing fees. Discover Stripe ACH fee caps (0.8% with $5 max), settlement speeds, reversal windows, and invoicing fee routing.

When invoicing commercial clients, agencies, freelancers, and B2B SaaS companies face a critical financial dilemma: Which payment rail should you offer your clients?
Allowing a corporate client to pay a $5,000 retainer via credit card instantly vaporizes $145.30 in merchant processing fees. Over a year of monthly retainers, that single client costs you $1,743.60 in credit card interchange fees—pure profit surrendered to card networks.
Switching that invoice to ACH Direct Debit caps the total processing cost at $5.00, keeping $140.30 in your bank account on every transfer.
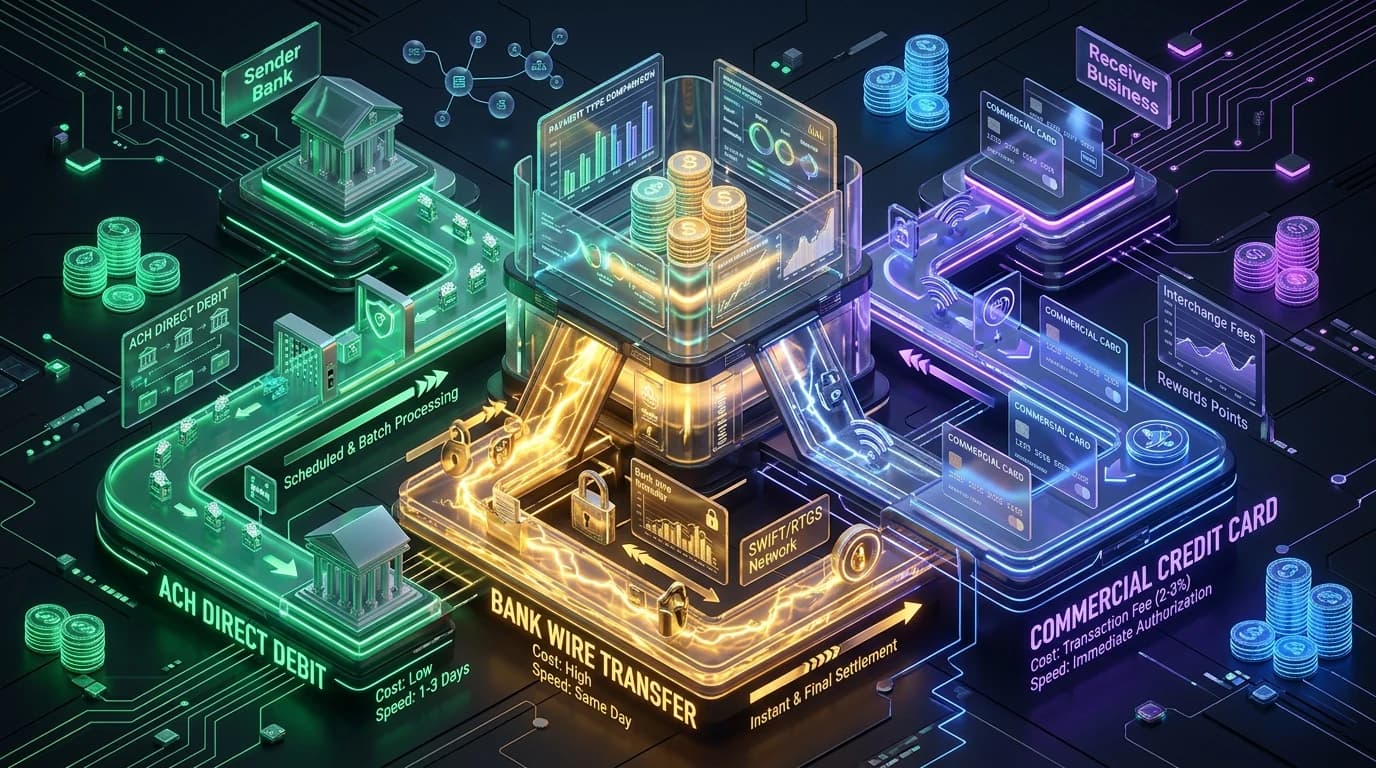
In this 2026 B2B payment guide audited by the FeeKit Financial Engineering Desk, we compare the three core commercial payment rails—ACH Direct Debit, Domestic Bank Wire Transfers, and Commercial Credit Cards—across cost structures, clearing speeds, dispute risks, and payment routing strategies. Generate your next compliant B2B invoice with our free PDF Invoice Generator.
1. Master Comparison Matrix: ACH vs. Wire vs. Credit Card#
Before diving into technical specifications, review how the three payment rails compare across the six primary financial dimensions:
| Dimension | ACH Direct Debit (Nacha) | Domestic Bank Wire (Fedwire) | Commercial Credit Card (Visa/Mastercard/Amex) |
|---|---|---|---|
| Typical Merchant Fee | 0.8% capped at $5.00 (Stripe) or $0.20 flat (Bank API) | $10 to $25 incoming fee (Fixed flat fee) | 2.9% + $0.30 (Uncapped percentage) |
| Maximum Fee Ceiling | Capped ($5.00 on most gateways) | Capped ($15–$25 regardless of amount) | Uncapped (Scales indefinitely with invoice size) |
| Settlement Time | 1 to 3 business days (Same-Day ACH available) | Near real-time (30 min to 2 hours) | Instant authorization; funds clear in 2 business days |
| Dispute / Reversal Risk | Low (Strict Nacha rules; 2 days for corporate CCD) | Zero (Irrevocable final settlement) | High (120-day chargeback window) |
| Payer Experience | Connect bank once via Plaid / Stripe Financial Connections | Manual wire initiation via payer's banking portal | Instant 16-digit card checkout |
| Optimal Invoice Range | $500 to $50,000+ | $10,000 to $1,000,000+ | Under $500 |
2. The Mathematical Impact Across Real Invoice Sizes#
To illustrate why payment rail selection matters, examine the actual dollar deductions across four common invoice amounts:
| Invoice Amount | Credit Card Fee (2.9% + $0.30) | Stripe ACH Fee (0.8%, $5 cap) | Bank Direct ACH ($0.25 flat) | Bank Incoming Wire ($15 flat) | Your Maximum Savings |
|---|---|---|---|---|---|
| $500.00 | $14.80 | $4.00 | $0.25 | $15.00 | $14.55 (ACH wins) |
| $2,500.00 | $72.80 | $5.00 (Capped) | $0.25 | $15.00 | $67.80 (ACH wins) |
| $10,000.00 | $290.30 | $5.00 (Capped) | $0.25 | $15.00 | $285.30 (ACH wins) |
| $50,000.00 | $1,450.30 | $5.00 (Capped) | $0.25 | $15.00 | $1,435.30 (Wire/ACH wins) |
The $10,000 Corporate Retainer Comparison:
• Credit Card (2.9% + 30¢): Net Payout = $9,709.70 (Loss: -$290.30)
• Stripe ACH Direct Debit:  Net Payout = $9,995.00 (Loss: -$5.00)
• Direct Bank Wire ($15):   Net Payout = $9,985.00 (Loss: -$15.00)

Annualized Difference (12 Monthly Payments):
Credit Card Total Fees: $3,483.60
ACH Direct Debit Total Fees: $60.00
Net Cash Retained: $3,423.60 back into your business!
Calculate your exact credit card processing deductions using the Stripe Fee Calculator.
3. Rail 1: ACH Direct Debit (The High-Margin Workhorse)#
The Automated Clearing House (ACH) network is the electronic payment backbone of the United States, administered by Nacha.
How ACH Direct Debit Works#
When your client pays via ACH Direct Debit, they authorize you to pull funds directly from their commercial checking account. Modern gateways like Stripe, Square, and QuickBooks utilize bank verification micro-deposits or instant API verification (via Plaid or Stripe Financial Connections).
Fee Breakdown#
- Gateway Providers (Stripe, Gusto, Wave): 0.80% per transaction, strictly capped at $5.00. Whether an invoice is $1,000 or $40,000, your processing fee never exceeds five dollars.
- Direct Commercial Bank Accounts (Mercury, Brex, Chase Business): Most modern fintech business accounts charge $0.00 or $0.20 to $0.50 flat per outgoing or incoming ACH transfer.
Nacha SEC Codes & Dispute Windows#
A vital legal distinction that protects B2B merchants:
- Consumer Accounts (PPD / WEB codes): Consumers have up to 60 calendar days from statement date to dispute an unauthorized debit.
- Corporate Accounts (CCD code): Commercial corporate accounts have only 2 business days to return an unauthorized ACH debit under Nacha operating rules. Once two business days pass, corporate ACH transfers cannot be casually reversed.
4. Rail 2: Bank Wire Transfers (The High-Value Fortress)#
A wire transfer is an electronic transfer of funds conducted directly between banks via real-time gross settlement systems like Fedwire (US Federal Reserve) or CHIPS (Clearing House Interbank Payments System).
Cost Structure#
Unlike ACH and credit cards, bank wire fees are typically fixed dollar amounts rather than percentages:
- Incoming Domestic Wire Fee: Your receiving bank charges between $10.00 and $25.00 (many modern platforms like Mercury and Relay offer $0 incoming domestic wires).
- Outgoing Wire Fee (Paid by Client): The client's bank typically charges them $20.00 to $35.00 to send a domestic wire.
- International Wire (SWIFT): Outgoing fees range from $35 to $50, with receiving intermediary bank fees ("landing fees") of $15 to $30.
When Wire Transfers Are Essential#
- Invoices Over $25,000: When moving large sums of capital, a $15 flat wire fee represents less than 0.06% of the transaction volume.
- Zero Dispute Tolerance: Wire transfers settle with immediate, irrevocable finality. Once the funds clear into your account, they cannot be retracted, bounced, or disputed.
- Same-Day Urgency: When contracts or project milestones require proof of immediate cleared funds before work begins, domestic wires clear within hours.
Learn how to structure clear payment milestones and contractual terms in our Invoice Payment Terms & Late Fees Guide.
5. Rail 3: Commercial Credit Cards (The Frictionless Tax)#
Credit cards offer the lowest friction for clients: no bank routing numbers, no login portals, and instant payment confirmation. However, for B2B merchants, credit cards present two serious financial liabilities: high uncapped percentages and long chargeback exposure.
The Corporate Interchange Penalty#
Most B2B clients pay using corporate purchasing cards (P-Cards) or premium executive rewards cards (e.g., Amex Business Platinum, Chase Ink). These cards carry the highest wholesale interchange rates in the card network system—often ranging from 2.50% to 3.10% interchange alone before processor markups.
If you accept credit cards on standard flat-rate pricing (2.9% + $0.30), your payment processor absorbs the interchange spread, but you still pay nearly 3% off your top line.
[!IMPORTANT] Level 2 and Level 3 Processing Data: If you invoice enterprise clients via credit card, use a processor that supports Level 2/3 data (passing purchase order numbers, line items, and tax identifiers). This qualifies corporate card transactions for discounted interchange rates, saving 0.50% to 1.00% per charge. Read more in our Interchange-Plus vs Flat-Rate Pricing Guide.
6. How to Build an Intelligent Payment Routing Strategy#
You do not need to ban credit cards entirely to protect your profits. Instead, implement a tiered B2B fee routing policy:
Rule 1: Set a Credit Card Threshold (e.g., $1,000)#
In your Master Services Agreement (MSA) or engagement terms, state that invoices over a designated threshold must be settled via ACH direct debit or bank wire.
- Invoices < $1,000: Credit card, ACH, or debit card accepted.
- Invoices ≥ $1,000: ACH Direct Debit or Wire Transfer required.
Rule 2: Pass Credit Card Surcharges (Where Permitted)#
If a client insists on using a corporate credit card to earn points on a $15,000 invoice, add a compliant credit card surcharge (typically 3.0%) to cover the merchant processing cost. In the US, credit card surcharging is legally permitted in most states as long as you disclose the fee prior to transaction completion. (Note: Surcharging debit cards is prohibited under federal law, and consumer card surcharging is illegal in the UK and EU).
Rule 3: Prominently Embed Bank Routing Details on Invoices#
Clients often default to credit cards simply because it is easier than requesting your wire instructions. When creating invoices with our Free Invoice Generator, include your:
- Bank Name
- Account Type (Business Checking)
- Routing Transit Number (ABA / ACH)
- Wire Routing Number (if different from ACH)
- Account Number
Providing these details directly in the invoice footer reduces payment delays and eliminates credit card processing deductions.
7. Summary: Which Payment Rail Should You Choose?#
- Use ACH Direct Debit if: You invoice between $500 and $25,000, manage ongoing monthly retainer agreements, or want to cap your transaction fee at $5.00 while keeping checkout frictionless for clients.
- Use Bank Wire Transfers if: The invoice exceeds $25,000, involves international clients, or requires guaranteed, irrevocable cleared funds before releasing deliverables.
- Use Credit Cards if: The transaction is under $500, represents an initial deposit for an emergency project, or the customer readily accepts an authorized processing surcharge.
Related Financial Precision Tools#
- Free PDF Invoice Generator — Create customized, compliant B2B invoices with clear ACH and wire instructions.
- Stripe Merchant Fee Calculator — Model domestic and international credit card deductions.
- Invoice Payment Terms & Late Fees Guide — How to enforce Net 15/30 terms and statutory late payment interest.
- Interchange-Plus vs Flat-Rate Pricing Guide — Cut merchant processing markups across high-volume transactions.
- Freelance Hourly Rate & Retainer Suite — Calculate profitable billing rates accounting for taxes, fees, and overhead.
- PayPal Commercial Fee Calculator — Compare PayPal invoice processing fees against standard credit cards.
Common Inquiries & Regulations
How much does it cost to accept an ACH Direct Debit payment?
Payment gateways like Stripe and QuickBooks charge 0.8% to 1.0% per ACH transaction, capped at a maximum fee of $5.00. Dedicated commercial bank ACH accounts (via Chase, Bank of America, or Mercury) charge a flat fee of $0.15 to $0.50 per batch transfer with zero percentage fee.
Why do credit cards cost so much more than ACH for large invoices?
Credit card processing charges an uncapped percentage (typically 2.9% + $0.30) because of interchange fees paid to the card issuing bank, network assessment fees (Visa/Mastercard), and cardholder rewards programs. On a $10,000 corporate invoice, credit card fees cost $290.30, whereas an ACH payment through Stripe is capped at just $5.00.
Is a bank wire transfer reversible or subject to chargebacks?
No. Unlike credit cards (which allow chargebacks up to 120 days) or consumer ACH payments (which allow unauthorized debit claims up to 60 days), wire transfers settle through the Federal Reserve Fedwire funds service and are final and irrevocable once credited. A customer cannot initiate a dispute or chargeback on a settled domestic wire transfer.
How long do ACH transfers take to settle compared to wire transfers?
Standard ACH transfers take 1 to 3 business days to clear through the Nacha network (Same-Day ACH clears within hours on business days). Domestic bank wire transfers settle in near real-time, typically within 30 minutes to 2 hours during Federal Reserve operating hours.
Can a B2B business legally require clients to pay via ACH or wire instead of credit cards?
Yes. In commercial B2B contracts, businesses have complete freedom to specify accepted payment rails in their engagement terms or Master Services Agreements (MSA). Many businesses accept credit cards only for invoices under $1,000 or require the client to cover card processing surcharges where permitted by state law.
Test These Numbers With Your Exact Transaction Data
Don't guess your margins. Use FeeKit's free, client-side financial precision tools to model your exact gross revenue, deductions, and tax compliance: