Stripe's Hidden Fees in 2026: 9 Charges You Won't Find on the 2.9% + 30¢ Pricing Page
The brutal mathematical truth of Stripe's real take-rate in 2026. Complete line-by-line breakdown of international card surcharges, 2% FX conversion spreads, Stripe Billing cuts, Radar fees, and the $15 non-refundable dispute penalty.

If you ask any startup founder, SaaS builder, freelance consultant, or e-commerce merchant what payment processing costs on Stripe, they will immediately quote the industry standard:
"It's just 2.9% plus 30 cents per transaction."
This single marketing bullet has made Stripe the undisputed operating system of modern internet commerce. It feels clean, transparent, and predictable.
Yet when founders audit their actual end-of-month bank deposits, their net payouts tell a wildly different story:
- An indie SaaS founder billing $15,000/month discovers their real processing drag was 4.4%.
- A digital agency collecting $50,000 across international clients discovers their real processing drag was 5.2%.
- A creator selling $10 e-books notices that card processing is eating over 7.1% of every sale.
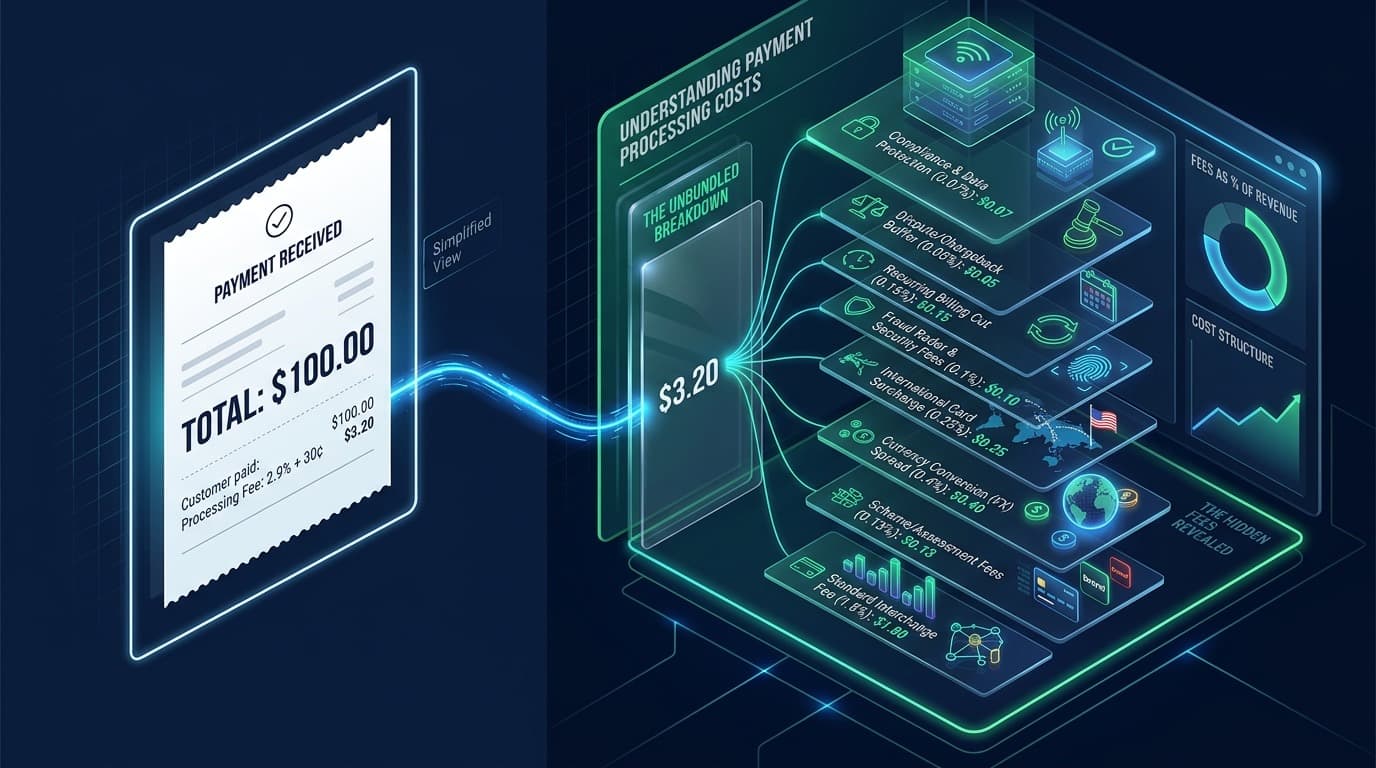
The reason is simple: 2.9% + 30¢ is merely the starting line. Beneath that headline rate lies an intricate ecosystem of unbundled micro-fees, cross-border surcharges, currency conversion margins, software usage cuts, and dispute penalties that quietly siphon thousands of dollars away from your bottom line every fiscal quarter.
In this comprehensive 2026 merchant audit by the FeeKit Financial Engineering Team, we dismantle the 9 hidden fees of Stripe, demonstrate the brutal mathematics with real transaction ledgers, and provide five proven architectural strategies to immediately reduce your processing costs.
You can audit your exact transactions in real time using our free Stripe Fee & Reverse Payout Calculator and compare alternative gateways with the Stripe vs PayPal vs Square Comparator.
1. The Baseline Illusion: Why 2.9% + 30¢ is Almost Never 2.9%#
Before looking at secondary surcharges, consider the mathematical distortion caused by the fixed $0.30 transaction fee.
Because the 30-cent fee is flat regardless of transaction size, your nominal fee diverges radically from your effective take-rate as cart values change:
Effective Fee Rate (%) = [ (Gross Order Amount × 0.029) + $0.30 ] ÷ Gross Order Amount × 100
Here is what that formula produces across common online order sizes:
| Order Amount | Fixed Fee | Variable (2.9%) | Total Stripe Cut | Real Effective Rate |
|---|---|---|---|---|
| $3.00 (Digital sticker/asset) | $0.30 | $0.09 | $0.39 | 13.00% |
| $5.00 (Coffee / Micro-SaaS) | $0.30 | $0.15 | $0.45 | 9.00% |
| $10.00 (Monthly subscription) | $0.30 | $0.29 | $0.59 | 5.90% |
| $25.00 (Standard consumer cart) | $0.30 | $0.73 | $1.03 | 4.12% |
| $50.00 (Software license) | $0.30 | $1.45 | $1.75 | 3.50% |
| $100.00 (Course / Professional tier) | $0.30 | $2.90 | $3.20 | 3.20% |
| $1,000.00 (Agency retainer / B2B) | $0.30 | $29.00 | $29.30 | 2.93% |
If you sell low-ticket digital downloads, memberships, or micro-transactions under $20, you are not paying 2.9%. You are handing Stripe between 4% and 13% of every transaction before factoring in a single secondary fee.
2. The 9 Hidden Fees Unbundled#
Now let us examine the nine ancillary fees that quietly stack on top of your baseline processing rate:
┌─────────────────────────────────────────────────────────────┐
│              STRIPE'S FULL TAKE-RATE STACK                  │
├─────────────────────────────────────────────────────────────┤
│  Baseline Domestic Card Fee            : 2.90% + $0.30      │
│  + International Card Surcharge        : +1.50%             │
│  + Currency Conversion (FX Spread)     : +1.00% to 2.00%    │
│  + Stripe Billing Platform Fee         : +0.50% to 0.80%    │
│  + Stripe Invoicing Surcharge          : +0.40% to 0.50%    │
│  + Stripe Tax Automated Calculations   : +0.50%             │
│  + Stripe Radar Advanced Fraud Score   : +$0.02 to $0.07/txn│
│  + Non-Refundable Dispute Charge       : $15.00 flat        │
│  + Instant Payout Convenience Fee      : 1.00% to 1.50%     │
├─────────────────────────────────────────────────────────────┤
│  REAL EFFECTIVE MERCHANT CUT           : 3.80% to 6.20%+    │
└─────────────────────────────────────────────────────────────┘
#1. The International Card Surcharge (+1.50%)#
If your Stripe account is based in the United States, and a customer in London, Toronto, Sydney, or Berlin pays using their local card, Stripe automatically applies a 1.5% international cross-border fee.
- Your 2.9% + 30¢ immediately becomes 4.4% + 30¢.
- On a $200 purchase, you pay $9.10 instead of $6.10.
For global SaaS companies and remote freelance consultants, 30% to 50% of customer volume is international—meaning your blended processing fee is automatically inflated by hundreds of dollars each month.
#2. The Currency Conversion FX Spread (+1.00% to 2.00%)#
If you charge an international customer in their local currency (e.g., charging a UK customer in GBP while your bank account is in USD), Stripe applies an additional 1.0% to 2.0% currency conversion markup.
Stripe converts the funds at a wholesale rate and adds their conversion spread on top. When combined with the 1.5% international card penalty:
- International Card Surcharge: +1.5%
- Currency Conversion Margin: +1.0% to 2.0%
- Baseline Processing: 2.9% + 30¢
- Total Gateway Deduction: 5.4% to 6.4% + $0.30
On a £500 ($650 USD equivalent) consulting invoice, Stripe deducts nearly $40 in fees alone—compared to less than $10 via a specialized cross-border provider like Wise vs Stripe.
#3. The Stripe Billing Software Tax (+0.50% to 0.80%)#
Many subscription SaaS businesses use Stripe Billing to manage recurring monthly customer subscriptions, upgrade prorations, and invoice dunning.
What many developers overlook in the fine print: Stripe Billing is not free.
- Starter Plan: Adds 0.50% on every recurring dollar processed after the first $100k lifetime.
- Scale Plan: Adds 0.80% on every recurring dollar processed.
This fee is stacked on top of the standard 2.9% + 30¢ card fee. If you process $50,000/month in recurring SaaS subscriptions on the Scale plan:
Stripe Billing Surcharge = $50,000 × 0.008 = $400.00 / month ($4,800 / year)
That is $4,800.00 per year purely for subscription logic—money deducted before server costs, marketing, or taxes.
#4. The Stripe Invoicing Surcharge (+0.40% to 0.50%)#
If you send hosted PDF invoices through Stripe's dashboard rather than using payment links or your own checkout page, Stripe charges an extra fee:
- First 25 invoices per month: Free
- All subsequent invoices: 0.40% to 0.50% per paid invoice
On a $5,000 freelance retainer invoice, that 0.4% surcharge costs you an extra $20.00, bringing total processing to $165.30 for sending a standard email invoice. You can completely avoid this penalty by using FeeKit's client-side Free PDF Invoice Generator and embedding a standard direct payment link.
#5. Stripe Radar for Fraud Teams ($0.02 to $0.07 per transaction)#
Stripe includes basic Radar fraud protection for free. However, if you upgrade to Radar for Fraud Teams to write custom block rules (such as blocking specific countries, IP subnets, or proxy networks), Stripe charges $0.02 to $0.05 per screened transaction.
Crucially: Stripe charges this fee even on failed or blocked transactions. If a botnet tests 10,000 stolen credit cards against your checkout form and Radar blocks all 10,000, you are still billed $200.00 to $500.00 for the automated screening.
#6. The Non-Refundable Dispute Charge ($15.00 Flat)#
When a customer files a chargeback through their credit card provider, Stripe debits the dispute amount from your balance plus a $15.00 dispute administration fee.
Here is the kicker: Even if you submit bulletproof proof of delivery and the bank rules in your favor, Stripe keeps the $15.00 fee.
Furthermore, if your chargeback dispute rate exceeds 1.0% of total transaction volume, card networks (Visa and Mastercard) place your merchant account into excessive chargeback monitoring programs, which trigger monthly penalties ranging from $1,000 to $10,000.
#7. Refund Fee Retentions: The Zero-Return Penalty#
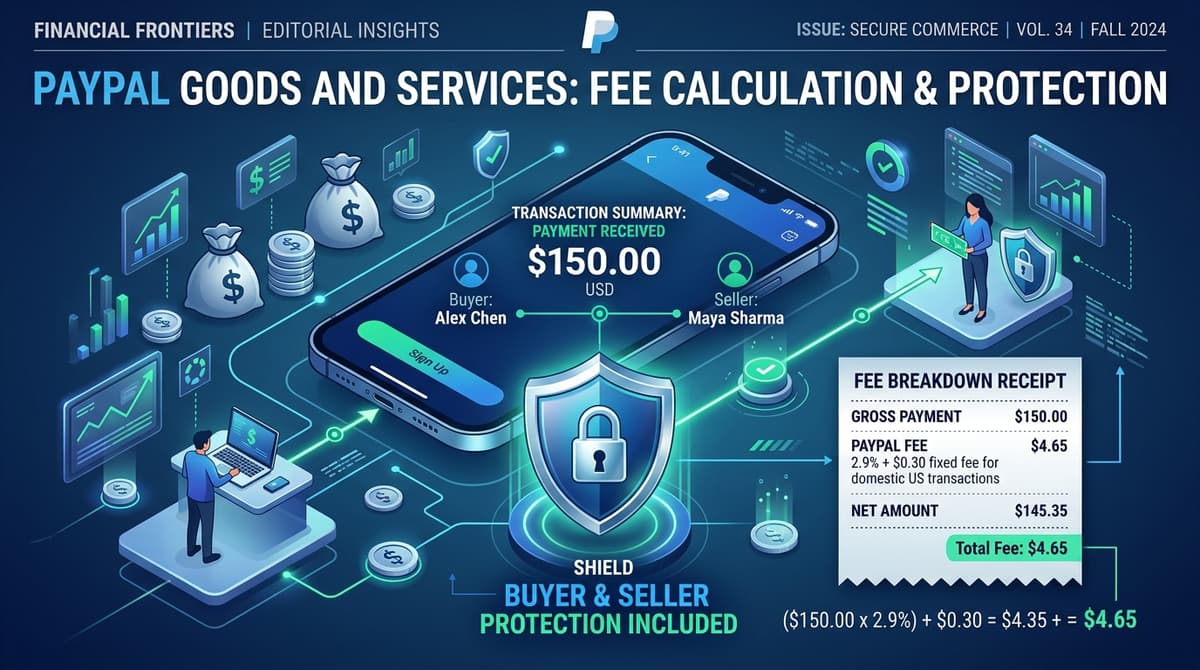
Prior to 2019, if a merchant refunded a $100 customer order, Stripe refunded the original $3.20 processing fee.
Stripe abolished fee refunds in late 2019.
Today, if a customer purchases a $500 item and cancels their order 10 minutes later:
- Stripe debited $14.80 upon initial payment.
- You refund the customer the full $500.00.
- Stripe permanently keeps the $14.80 fee.
- You are out-of-pocket $14.80 for a transaction where you earned $0.00.
In e-commerce verticals with 15% to 20% return rates (such as fashion or consumer apparel), this non-refunded fee policy directly reduces gross margins by 0.6% to 1.2% across your entire catalog.
#8. Instant Payout Surcharges (1.0% to 1.5%)#
Standard Stripe bank payouts operate on a rolling 2-business-day schedule (or longer in certain international regions). If you need immediate cash flow to pay contractor invoices or ad spend, Stripe offers Instant Payouts to an eligible debit card.
The cost? 1.0% to 1.5% of the transfer volume (with a $0.50 minimum). Transferring $10,000 instantly costs $100.00 to $150.00—an annualized APR equivalent to a high-interest payday advance.
#9. Stripe Tax Automated Collection (+0.50%)#
Stripe Tax monitors your sales across US states and international VAT jurisdictions, calculating rates in real time at checkout.
While convenient, it costs an extra 0.50% per transaction in states or countries where you have tax collection enabled. If you are already paying 2.9% + 30¢ plus 0.5% for Billing, adding Stripe Tax pushes your default baseline to 3.9% + 30¢ on every domestic sale.
3. The Ledger Audit: A Real $50,000/Month SaaS Business#
To see how these micro-fees accumulate in practice, let us examine the monthly statement of a modern B2B SaaS startup processing $50,000 across 1,000 customer subscriptions:
| Revenue / Fee Component | Volume / Rate | Total Deducted | % of Gross |
|---|---|---|---|
| Gross Invoiced Revenue | 1,000 subscriptions ($50 avg) | +$50,000.00 | 100.00% |
| Baseline Card Processing | 2.9% on $50,000 | -$1,450.00 | -2.90% |
| Fixed Transaction Charges | 1,000 transactions × $0.30 | -$300.00 | -0.60% |
| International Card Penalties | 350 transactions ($17,500) × 1.5% | -$262.50 | -0.53% |
| Currency Conversion Margins | 200 non-USD txns ($10,000) × 1.5% | -$150.00 | -0.30% |
| Stripe Billing (Scale Plan) | 0.8% on $50,000 | -$400.00 | -0.80% |
| Radar Custom Screening | 1,000 transactions × $0.02 | -$20.00 | -0.04% |
| Customer Refunds (3%) | 30 refunded txns ($1,500) — fees lost | -$52.50 | -0.11% |
| Chargeback Disputes | 2 disputed charges × $15.00 | -$30.00 | -0.06% |
| Total Stripe Deductions | Sum of all gateway friction | -$2,665.00 | -5.33% |
| Net Bank Deposit | Actual Cash in Bank | $47,335.00 | 94.67% |
Notice the critical revelation: The founder anticipated paying $1,750.00 (3.5% nominal). In reality, Stripe deducted $2,665.00—an extra $915.00/month ($10,980.00 annually) lost to secondary fees.
4. Five Strategies to Cut Stripe Fees by 30% to 70%#
You do not have to accept these deductions as an inevitable cost of doing business online. Here are five practical engineering and accounting strategies to immediately recapture profit:
Strategy 1: Route B2B Invoices Through ACH Direct Debit ($5 Cap)#
If you bill clients or customers for amounts exceeding $500, never accept credit cards as the default payment method.
Stripe supports ACH Direct Debit in the United States:
- Fee: 0.80% capped at a maximum of $5.00
Let us compare the cost of processing a $3,000 agency retainer or enterprise software seat:
- Credit Card (2.9% + 30¢): Fee = $87.30
- ACH Direct Debit (0.8% capped at $5): Fee = $5.00
- Direct Cash Savings: $82.30 on a single invoice (a 94.3% savings)
If you process twenty $3,000 invoices monthly, switching from cards to ACH saves $1,646.00 every month—over $19,700 per year directly added to your net profit.
Strategy 2: Open Local Multi-Currency Settlement Accounts#
If you have substantial customer volume in the UK, Europe, or Canada, avoid Stripe's 1.5% to 2.0% currency conversion markup by configuring multi-currency bank accounts.
- Open a multi-currency business account through Wise Business, Airwallex, or Mercury.
- In your Stripe dashboard under Settings > Bank Accounts, add dedicated settlement accounts for GBP, EUR, and CAD.
- Stripe will deposit British Pounds directly into your GBP account without converting to USD, bypassing the foreign exchange penalty entirely.
Strategy 3: Implement Surcharging or Cash Discounting#
In 46 out of 50 US states (and throughout B2B international commerce), merchants are legally permitted to pass credit card processing costs to customers or offer a 3% cash discount for bank transfers (ACH).
By presenting two payment options on your checkout page:
- Pay with Bank Transfer / ACH: $1,000.00 (No fee)
- Pay with Credit Card: $1,030.00 (Includes card convenience buffer)
You protect 100% of your gross margins while giving clients a clear, legitimate financial incentive to pay via low-cost bank rails.
Strategy 4: Bypass Stripe Invoicing and Self-Host Your Bills#
Do not pay Stripe an extra 0.4% to 0.5% on every paid invoice simply to generate a hosted PDF link.
Use FeeKit's 100% client-side, encrypted Free Invoice Generator to generate clean, professional, branded PDF invoices with statutory payment terms. Simply paste your Stripe Payment Link or ACH routing details directly into the payment instructions box. You get institutional-grade invoices with zero platform fees.
Strategy 5: Negotiate Interchange-Plus Pricing at $80k+/Month#
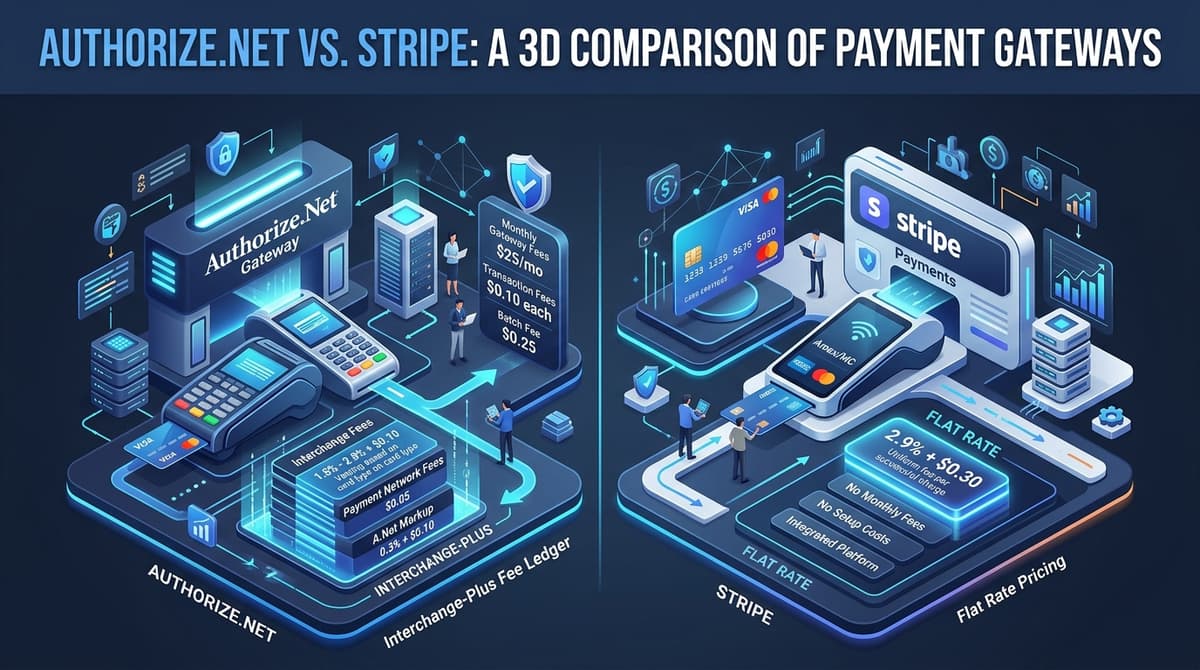
Once your business consistently processes $80,000 to $100,000 monthly, reach out to your Stripe account representative (or use Stripe's enterprise sales contact) to request Interchange-Plus (IC+) pricing.
Under Interchange-Plus:
- You pay the raw, interchange fee set by Visa/Mastercard (averaging 1.4% to 1.8% for standard consumer cards)
- Plus a small fixed Stripe markup (typically 0.15% to 0.30% + $0.10)
This immediately drops your blended processing rate from 2.9% down to 2.1% to 2.3%, saving thousands of dollars annually as your transaction volume scales.
The Bottom Line#
Stripe remains one of the finest payment infrastructures ever built for internet software. Its developer APIs, uptime reliability, and global reach are world-class.
However, treating Stripe as a simple "2.9% utility" is a dangerous financial mistake. In 2026, building a profitable digital business requires understanding your true blended take-rate, monitoring ancillary charges, and routing large transactions through high-margin bank rails.
Audit your current payment charges today with FeeKit's interactive tools:
- Calculate exact merchant cuts with the Stripe Fee Calculator
- Compare Stripe against competitors using the Stripe vs PayPal vs Square Comparator
- Protect product margins with the Profit Margin & Markup Engine
Common Inquiries & Regulations
What is Stripe's true effective fee percentage in 2026?
While Stripe markets a baseline domestic rate of 2.9% + $0.30, the true effective merchant take-rate typically ranges between 3.8% and 5.9%. This increase is driven by cross-border card penalties (+1.5%), currency conversion spreads (+1% to 2%), Stripe Billing software cuts (+0.5% to 0.8%), Stripe Tax (+0.5%), and fixed transaction fees on lower order values.
Does Stripe refund processing fees when a merchant issues a customer refund?
No. Since late 2019, Stripe permanently retains the entire original processing fee (both the 2.9% variable cut and the $0.30 fixed surcharge) whenever you refund a customer. If a customer buys a $100 product and demands a refund, Stripe keeps $3.20, and you must pay that difference out of pocket.
Does Stripe charge $15 for disputes even if the merchant wins?
Yes. Stripe assesses a non-refundable $15.00 chargeback fee the moment a customer files a payment dispute with their card-issuing bank. Even if you submit exhaustive proof of delivery and the bank rules 100% in your favor, Stripe does not refund the $15.00 administrative fee.
How much cheaper is ACH Direct Debit on Stripe compared to credit cards?
ACH Direct Debit on Stripe costs 0.8% capped at a maximum of $5.00 per transaction. On a $2,000 B2B invoice, credit card processing costs $58.30 (2.9% + $0.30), whereas ACH Direct Debit costs exactly $5.00, saving $53.30 (a 91.4% cost reduction) on a single invoice.
At what processing volume can you negotiate lower custom rates with Stripe?
Stripe generally opens custom volume and Interchange-Plus pricing negotiations once a business consistently exceeds $80,000 to $100,000 per month in gross transaction volume (approx. $1,000,000+ annually), or for companies with high average order values ($500+).
Test These Numbers With Your Exact Transaction Data
Don't guess your margins. Use FeeKit's free, client-side financial precision tools to model your exact gross revenue, deductions, and tax compliance: